In short: the pre-deposit is 10 per cent of the disputed tax only, a pre-deposit won on appeal is refundable unless a stay is obtained, and Rule 96(10) demands can be closed under Circular 264. Rule 86A blocking and Rule 159 attachment now carry objection routes.
Before you file a GST appeal you need to know what to deposit, when it comes back and what to do about a blocked ledger. Circulars 259 and 264 settle several long-running questions, and the revised rules add objection routes for blocking and attachment.
What Circulars 259 and 264 Settle
There has been uncertainty over what the pre-deposit should be computed on, and over whether a refund of pre-deposit can be withheld after the appellant wins because the department intends to appeal further. Circular No. 259/05/2026-GST dated 26/10/2026 answers six questions on this. The Rules add an objection route against blocking of the electronic credit ledger and a reasoned decision on objections to provisional attachment, and Circular No. 264/10/2026-GST settles the Rule 96(10) dispute.
Computing the Pre-Deposit (Circular 259)
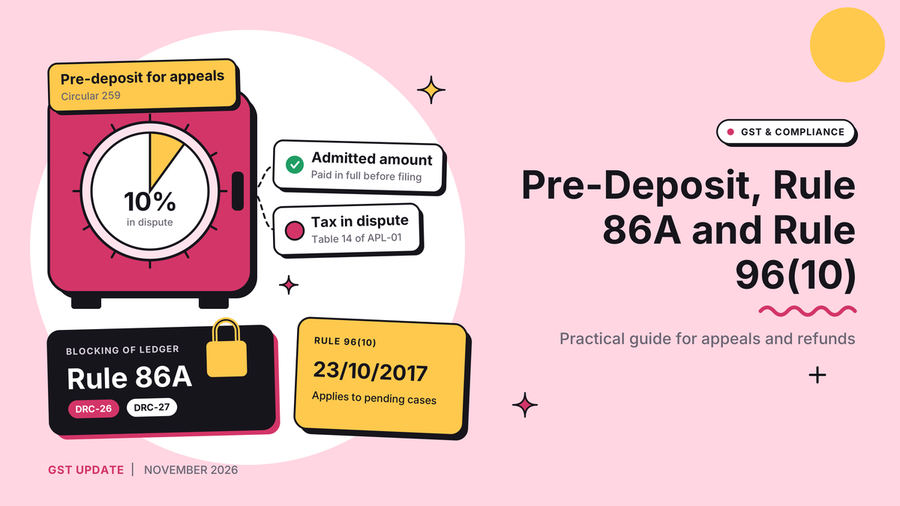
- Admitted amount: the part of tax, interest, fine, fee and penalty the taxpayer accepts and will not appeal. It is paid in full before filing.
- Tax in dispute: the balance tax the taxpayer contests. The pre-deposit is 10 per cent of this tax alone.
- The split is the taxpayer's choice at filing and is shown in Table 14 of APL-01 or Table 20 of APL-05.
- Tribunal appeal: 10 per cent of the tax confirmed by the Appellate Authority and disputed by the appellant, in addition to the amount already paid for the first appeal.
- Both deposits are subject to the maximum amounts prescribed in Sections 107(6) and 112(8) of the CGST Act.
Worked example (illustrative figures, not a real case): on a Rs.50 lakh tax demand, the taxpayer admits Rs.10 lakh and disputes Rs.40 lakh. The admitted Rs.10 lakh is paid in full. The pre-deposit is 10 per cent of Rs.40 lakh, which is Rs.4 lakh, against Rs.5 lakh if the full demand were disputed (interest and penalty ignored for simplicity).
Refund of Pre-Deposit
- No direction needed: an appellate order in the taxpayer's favour need not mention the refund. It is claimed in RFD-01 under "on account of order" (S. No. 7) on receipt of the order.
- Department's appeal: the refund is payable unless the order is stayed by the Tribunal or a Court. An intention to appeal, or even an appeal filed, is not a ground to withhold it.
- Interest under Section 115: runs from the actual date of each payment, computed separately for the first-appeal deposit and the Tribunal deposit.
- Remand: on a full remand, the refund is made within the prescribed time. On a partial remand with part of the demand upheld, the confirmed amount with interest is recovered or adjusted against the pre-deposit and the balance refunded.
Blocking of the Credit Ledger: Rule 86A from 01/04/2027
Earlier, the Commissioner or an officer not below Assistant Commissioner could block the ledger with no form and no objection route, for one year. From 01/04/2027, the order is issued in DRC-26 by the proper officer with reasons and stays in force for one year or until lifted earlier. The taxpayer objects in DRC-27. After a hearing, the officer issues DRC-28, where Part A allows debit and Part B rejects the objection with reasons. Until then, a blocking order continues to be contested through a representation to the Commissioner or a writ.
To see what a blocking order affects, track your electronic cash, credit and liability ledger balances in one place with GST ledger reports.
Provisional Attachment: Rule 159 from 01/11/2026
The attachment order is issued in Part A of FORM GST DRC-22. An objection under Rule 159(5) can be rejected only by a reasoned order in Part B of DRC-22 after hearing the person. Earlier, the objection could be left undecided with the attachment continuing.
Rule 96(10) and the Omission from 23/10/2017 (Circular 264)
Rule 96(10) barred the IGST refund route to exporters who procured inputs under Advance Authorisation, EOU and similar notifications. It was omitted from 08/10/2024 prospectively, and demands to recover IGST refunds for the earlier period continued. Following the Supreme Court in Goodluck India Ltd. (06/08/2026), an omission without a saving clause applies to pending proceedings. The omission is therefore treated as operating from 23/10/2017, and the same treatment applies to Rules 89(4A) and 89(4B).
Pending demands and refund rejections, at adjudication or in appeal, can be closed on the circular itself. Where recovery has already been made, a refund application on account of order lies.
How WhiteBooks Helps You Prepare for an Appeal
Appeals are won on records and deadlines. WhiteBooks supports both.
- Size the tax in dispute using notice-wise exposure from the Financial Exposure Report in GST notice management software.
- Keep appeal and reply deadlines visible alongside the notice.
- Developers can pull cash and ITC ledger balances programmatically through the GST API.
A3 Advisors LLP
A3 Advisors LLP is an entrepreneurial tax and business consulting firm led by Big 4 alumni. The firm offers holistic solutions across direct tax, transfer pricing, indirect tax, valuations, corporate law and virtual CFO services.