In short: from 01/11/2026, ITC on eligible input services counts in Net ITC for inverted duty refunds, and from 01/04/2027 ITC on capital goods counts too. In the worked example below, the maximum refund rises from Rs.2.2 lakh to Rs.5.8 lakh.
If the GST rate on your inputs is higher than the rate on your output, this change decides how much of your accumulated credit you can claim back as a refund. Manufacturers, job-work-heavy businesses and exporters of goods should review their credit balances against the new definition of Net ITC before their first claim under the revised rules.
Why Inverted Duty Refunds Were Narrower Than the Problem
An inverted duty structure arises when the GST rate on inputs is higher than the rate on the output. Until now, the refund under Rule 89(5) was computed on Net ITC that covered only ITC on inputs, meaning goods. Input services such as job work and freight, and the ITC on capital goods, stayed in the electronic credit ledger even where the inversion was real.
The revised rules change that. The eligibility test is unchanged: the inversion must be caused by goods inputs taxed at a higher rate than the output. What changes is the content of Net ITC.
What Changes in Net ITC
The formula for the maximum refund amount is the same: turnover of the inverted rated supply multiplied by Net ITC and divided by adjusted total turnover, less the tax payable on the inverted rated supply. Net ITC is now built as follows:
- Earlier: ITC on inputs (goods) availed during the relevant period.
- From 01/11/2026: ITC on inputs plus ITC on eligible input services availed on or after 01/11/2026.
- From 01/04/2027: the above plus ITC on capital goods attributable to the period, availed on or after 01/04/2027.
Only credit that is validly availed counts. ITC blocked under Section 17(5) never enters Net ITC.
Worked Example: Inverted Duty Refund Before and After 01/11/2026
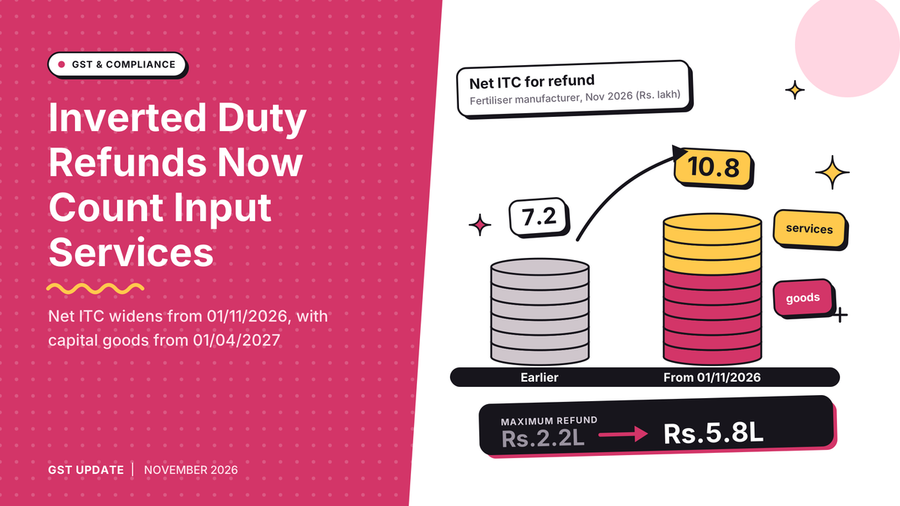
These are illustrative figures, not a real taxpayer’s case, and they only show the method. A fertiliser manufacturer sells output worth Rs.100 lakh at 5 per cent, so output tax is Rs.5.0 lakh. In November 2026 it buys raw material worth Rs.40 lakh at 18 per cent (ITC Rs.7.2 lakh) and job work, freight and other input services worth Rs.20 lakh at 18 per cent (ITC Rs.3.6 lakh). It has no other turnover.
- Earlier: Net ITC for refund is Rs.7.2 lakh, the maximum refund is Rs.2.2 lakh, and Rs.3.6 lakh of ITC stays stuck in the ledger.
- Now: Net ITC is Rs.10.8 lakh, the maximum refund is Rs.5.8 lakh, and no ITC is left stuck.
- The 90 per cent provisional refund, available within 3 working days, works out to Rs.5.22 lakh.
Before you apply the method to your own numbers, confirm the rate on each input with the free GST HSN and SAC code search and cross-check the tax amount in the GST tax calculator.
Capital Goods and the 1/60th Rule
Capital goods ITC attributable to a period is 1/60 of the eligible ITC on capital goods, multiplied by the number of months in the period, less reversals for those months. It is counted for 60 months from the month of availment. For example, a machine bought with ITC of Rs.12 lakh (an illustrative figure) therefore adds Rs.0.2 lakh to Net ITC for each month of the claim.
Two conditions apply. Only ITC availed on or after 01/04/2027 enters the refund, and the claim must carry a declaration that the goods are in use and have not been sold or removed.
Related Changes for Exporters of Goods
- The 90 per cent provisional refund now covers inverted duty structure claims.
- The cap of 1.5 times the value of like goods supplied domestically on the refund for export of goods is removed from 01/11/2026.
- The Rs.1,000 floor under Section 54(14) no longer stops refund claims, including on export of goods with payment of tax.
How WhiteBooks Helps You Prepare a Refund-Ready ITC Position
A refund claim is only as strong as the ITC data behind it. WhiteBooks GST software keeps your input tax credit reconciled with what your suppliers have reported, so the credit you count in Net ITC is credit you can defend.
- Match purchase invoices with GSTR-2B through GSTR-2B reconciliation, which sorts invoices into Safe to Claim, Needs Review and Cannot be Claimed.
- Review claimed and available credit with the GSTR-2B vs 3B ITC reports before you build the Net ITC figure.
- Record purchase invoices and expenses, including job work and freight, in WhiteBooks GST accounting software so your books are ready when you prepare the refund workings.
A3 Advisors LLP
A3 Advisors LLP is an entrepreneurial tax and business consulting firm led by Big 4 alumni. The firm offers holistic solutions across direct tax, transfer pricing, indirect tax, valuations, corporate law and virtual CFO services.