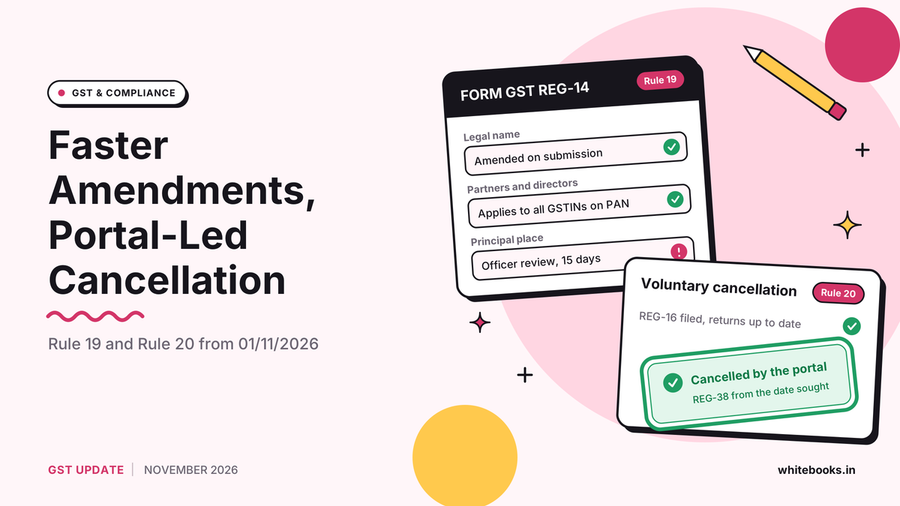
In short: since 01/11/2026 only a change of principal place of business goes to the officer under Rule 19, and Rule 20 adds time limits and deemed outcomes to voluntary cancellation. The revised REG-16 and some new forms follow on 01/12/2026 and 01/04/2027.
Changing your legal name, adding a place of business or closing a registration used to mean waiting for an officer. Since 01/11/2026 most amendments stand on submission, and cancellation on request now has time limits and deemed outcomes. This guide shows what applies to you and when.
Two Substituted Rules, in Force from 01/11/2026
Before the revision, every change in a core field such as legal name, place of business, partners or directors waited for the officer's approval, and the officer faced no consequence for delay in deciding an application for cancellation. Substituted Rule 19 (amendment) and Rule 20 (cancellation on request) move most of this to the system and add time limits with deemed outcomes.
What Applies When
- 01/11/2026: substituted Rule 19 (amendment) and Rule 20 (cancellation on request).
- 01/12/2026: the revised REG-16, and system handling of the principal place of business for Rule 14A registrants.
- 01/04/2027: the new forms REG-34 to REG-37 for changing the effective date of cancellation.
Amendment of Registration: Rule 19
The taxpayer files FORM GST REG-14 within 15 days of the change, with the documents.
- Principal place of business: this change alone goes to the officer. The officer has 15 days, may issue REG-03 within 15 days, and the taxpayer replies in REG-04 within 7 working days. If the officer takes no action within 15 days of the application or 7 working days of the reply, the registration is deemed amended. If the taxpayer does not reply, the application is deemed rejected (REG-05A).
- Everything else: legal name, partners, directors, additional places of business and all other particulars stand amended on submission after online validation.
- Rule 14A registrants: the principal place of business is also handled by the system from 01/12/2026.
The effective date is the date of approval where the officer is involved. For system-amended fields, the date of submission is the effective date, so invoices and e-way bills should carry the new particulars from that date. If the principal place is changed along with other fields in one application, the whole application travels to the officer, so filing the other changes separately keeps them out of the queue.
After an amendment, update the party and GSTIN details in your billing system so that e-invoices and e-way bills carry the new particulars from the effective date.
Voluntary Cancellation: Rule 20
The earlier position was simple: apply in REG-16 within 30 days, the officer had 30 days to pass an order in REG-19 with no consequence for not doing so, and GSTR-10 followed within three months. The revised position works as follows:
- All returns up to the date of cancellation must be filed, including GSTR-3B wherever GSTR-1 or IFF is filed.
- REG-16 is filed within 30 days of the event. The 30-day limit does not apply on the death of a proprietor. The registration is suspended on submission, and remaining returns are filed by their due dates.
- Cases that meet the Rule 20 conditions on the Rs.2.5 lakh B2B output tax limit or on GSTR-10 filing: the portal cancels the registration in REG-38 from the date sought, without the officer. Read the exact conditions in Rule 20 before relying on this route.
- All other cases: the officer issues REG-19 or REG-03 within 15 days, the taxpayer replies in REG-04 within 15 days, and the officer approves or rejects (REG-05) within 15 days. No action in 15 days means the application is deemed approved.
Changes to the Revised REG-16 from 01/12/2026
The revised REG-16 carries a closed list of reasons. Transfer of business, including on death of the proprietor or on amalgamation or demerger, is a reason by itself, and "Others" is dropped. The form also offers an option to file NIL returns for the unfiled period up to the cancellation date, and the ITC reversal on stock and capital goods is computed and paid in the form itself.
Changing the Effective Date After Cancellation
Under the revised cancellation provisions, the effective date of cancellation can be changed once. The officer issues a show cause notice in REG-34, the taxpayer replies in REG-35 within 30 days, and the officer drops the proceeding (REG-36) or changes the date (REG-37) within 30 days of the reply, or within 60 days of the notice if there is no reply. If no order is passed in 60 days, the proceeding is deemed dropped. These forms are inserted from 01/04/2027 even though Rule 20(14) to (20) apply from 01/11/2026. Until the forms are live, an earlier-date proceeding would go on the existing REG-17 route.
How WhiteBooks Helps You Keep Registration Details in Step
Registration details feed every invoice, return and e-way bill you issue, so a change on the portal needs a matching change in your records.
- Verify the legal name, trade name and registration status of any GSTIN with the free GST number search and GSTIN verification tool, or check several numbers at once with multiple GST number search.
- Keep customer and vendor details current in the party master so documents carry the right particulars.
- File the pending returns before cancellation through WhiteBooks GST software.
A3 Advisors LLP
A3 Advisors LLP is an entrepreneurial tax and business consulting firm led by Big 4 alumni. The firm offers holistic solutions across direct tax, transfer pricing, indirect tax, valuations, corporate law and virtual CFO services.