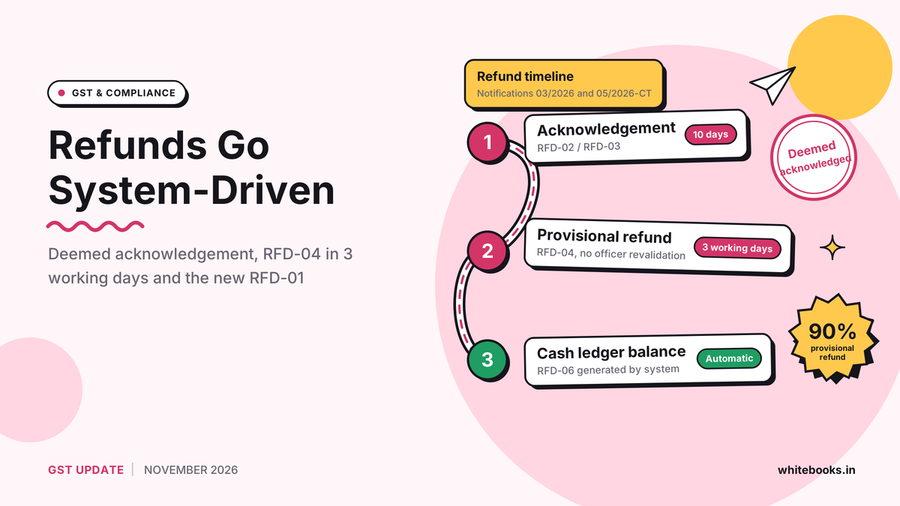
In short: from 01/11/2026 the portal, not the officer, generates the refund acknowledgement, the provisional refund and the cash ledger refund within fixed days. The new FORM GST RFD-01 from 01/12/2026 asks for invoice-level data, so reconcile before you file.
Refunds Move from the Officer to the System
Under the revised procedure effective 01/11/2026, acknowledgement, provisional refund and refund of the cash ledger balance are generated by the portal within fixed days. Where the officer does not act, the application is deemed acknowledged. The practical result is that the speed of a refund depends more on the quality of the data filed than on an officer's workload.
Stage-Wise Comparison
Acknowledgement (RFD-02 or RFD-03):
- Earlier: issued within 15 days of filing. If neither an acknowledgement nor a deficiency memo was issued, the application simply stayed pending.
- Now: issued within 10 days of filing. If neither issues in that time, the application is deemed acknowledged and the 60 days for the final order run from the date of filing.
Provisional refund (RFD-04 or RFD-05):
- Earlier: the officer sanctioned 90 per cent of zero-rated claims within 7 days of acknowledgement, after scrutiny.
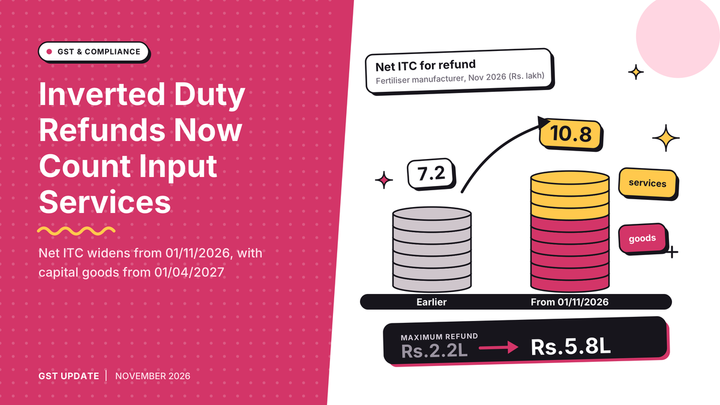
- Now: the system generates RFD-04 within 3 working days of acknowledgement on risk evaluation, with no revalidation by the officer, and the payment order follows from the portal. The 90 per cent provisional refund also covers inverted duty structure claims.
Final order (RFD-06):
- Refund of excess balance in the cash ledger is sanctioned by the system. RFD-06 is generated automatically after adjusting any outstanding demand, with no officer involvement.
- Every other refund (ITC, exports, inverted duty) stays with the officer, who passes the order within 60 days as before.
The New FORM GST RFD-01 from 01/12/2026
The new form changes the supporting documents:
- Statements 1A, 3 and 5 (outward supplies): complete particulars of each invoice and shipping bill, including value, HSN, port, EGM, and BRC or FIRC, not only the number and date.
- Annexure 3 (inward supplies): invoice-wise ITC with the Section 17(5) and eligibility flags and the GSTR-2B period. It becomes part of the form in place of the Excel Annexure B.
- Statement 1B (new): a separate claim for ITC accumulating on 0.1 per cent supplies to merchant exporters, with the recipient's shipping bill and EGM details.
- Non-prosecution declaration: furnished with every claim, not only for the provisional refund.
- Declaration on capital goods (from 01/04/2027): capital goods in the claim are in use for the zero-rated or inverted supplies and have not been sold.
Why Data Quality Now Decides Speed
The procedure turns on the risk score the system assigns to the application, and the officer steps in only where the system routes the claim for review. Clean, invoice-level data keeps the claim on the system track.
A3 Advisors LLP
A3 Advisors LLP is an entrepreneurial tax and business consulting firm led by Big 4 alumni. The firm offers holistic solutions across direct tax, transfer pricing, indirect tax, valuations, corporate law and virtual CFO services.